All Categories
Featured

How Indexed Universal Life Policies Secure Retirement
That flexibility can be big if your income changes from year to year, or you go through a huge life event (such as divorce or short-lived work leave) and still wish to keep your policy in force. It also implies you'll require to pay closer attention to your policy over time.

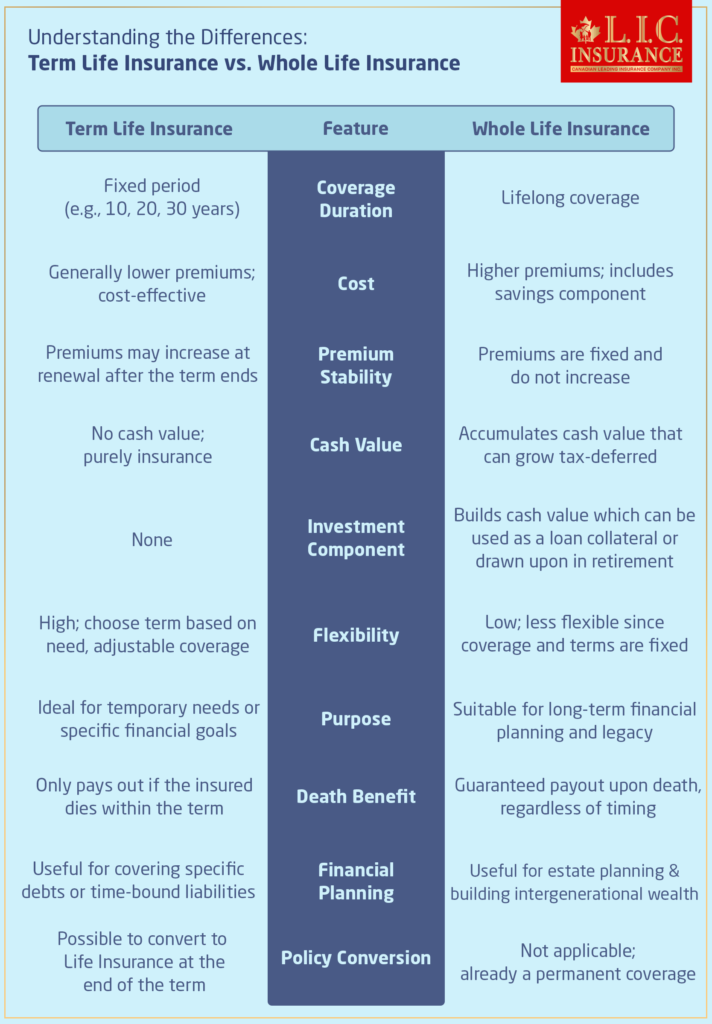
This table highlights the biggest distinctions: Both whole life insurance and indexed universal life supply you with irreversible coverage that constructs money worth, but how that money worth grows is quite various. Entire life insurance normally has actually ensured development at a set rate, while IUL has the capacity for greater returns since its cash value is connected to a market index.
Term life insurance coverage is generally the most cost effective and easiest kind of life insurance to get. It doesn't build cash value, however you get a guaranteed death advantage for a set time period, typically at a portion of the cost of an IUL policy. You can consider a variable universal life insurance policy as one step above an IUL policy in regards to threat and benefit.
This indicates you'll have greater development capacity however also the possibility of investment losses. Like any monetary product, indexed universal life insurance has advantages and trade-offs. If your primary goal is simply changing your earnings for your household, a term life insurance policy is generally simpler and far less costly.
Choosing Whole Life versus Term Benefits
Common costs may include:, which normally increases as you age for handling the policy deducted from your payments if you add features like long-term care or persistent health problem benefits if you cancel the policy throughout its early years Before you purchase an indexed universal life policy, the insurance provider will typically supply an illustration revealing how your policy could perform gradually.

Latest Posts
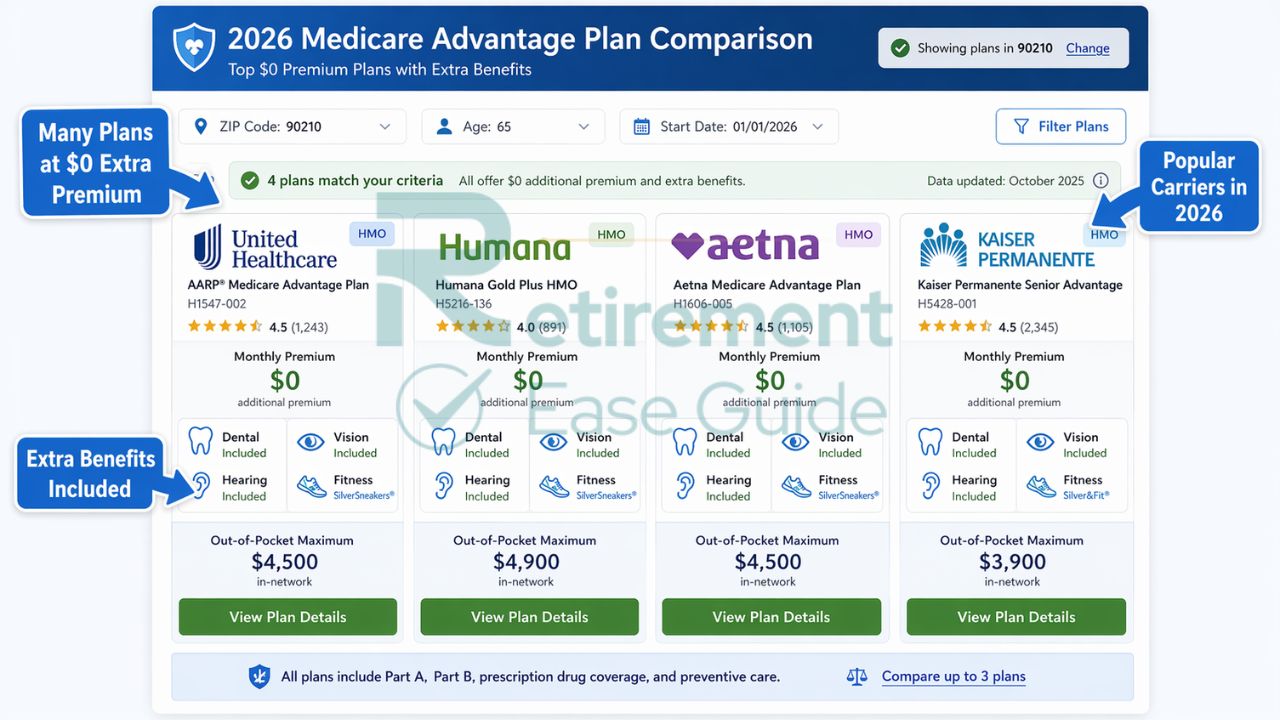
Selecting 2026 Medicare Advantage Coverage Options
How Indexed Universal Life Policies Secure Retirement
Comparing PPO Vs HMO Medical Insurance for 2026